What the numbers say
The state's own figures describe a market that has stabilised:
- In January 2026, Florida's insurance regulator reported that 17 new insurers had entered the state since the reforms of 2022 and 2023.
- Citizens, the state-backed insurer of last resort, cut its average homeowners rate by 8.8% for 2026, and its wind-only rate by 5.5%, from July 1.
- Citizens has shrunk from about 1.4 million policies at the end of 2023 to roughly 274,000 in June 2026. For the 2026 hurricane season it bought $2.82 billion of reinsurance.
- By the end of July, regulators reported that home insurance rates had fallen in 51 counties this year. Florida nonetheless remains the most expensive state in the country to insure a home.
Why your own premium may not follow the headline
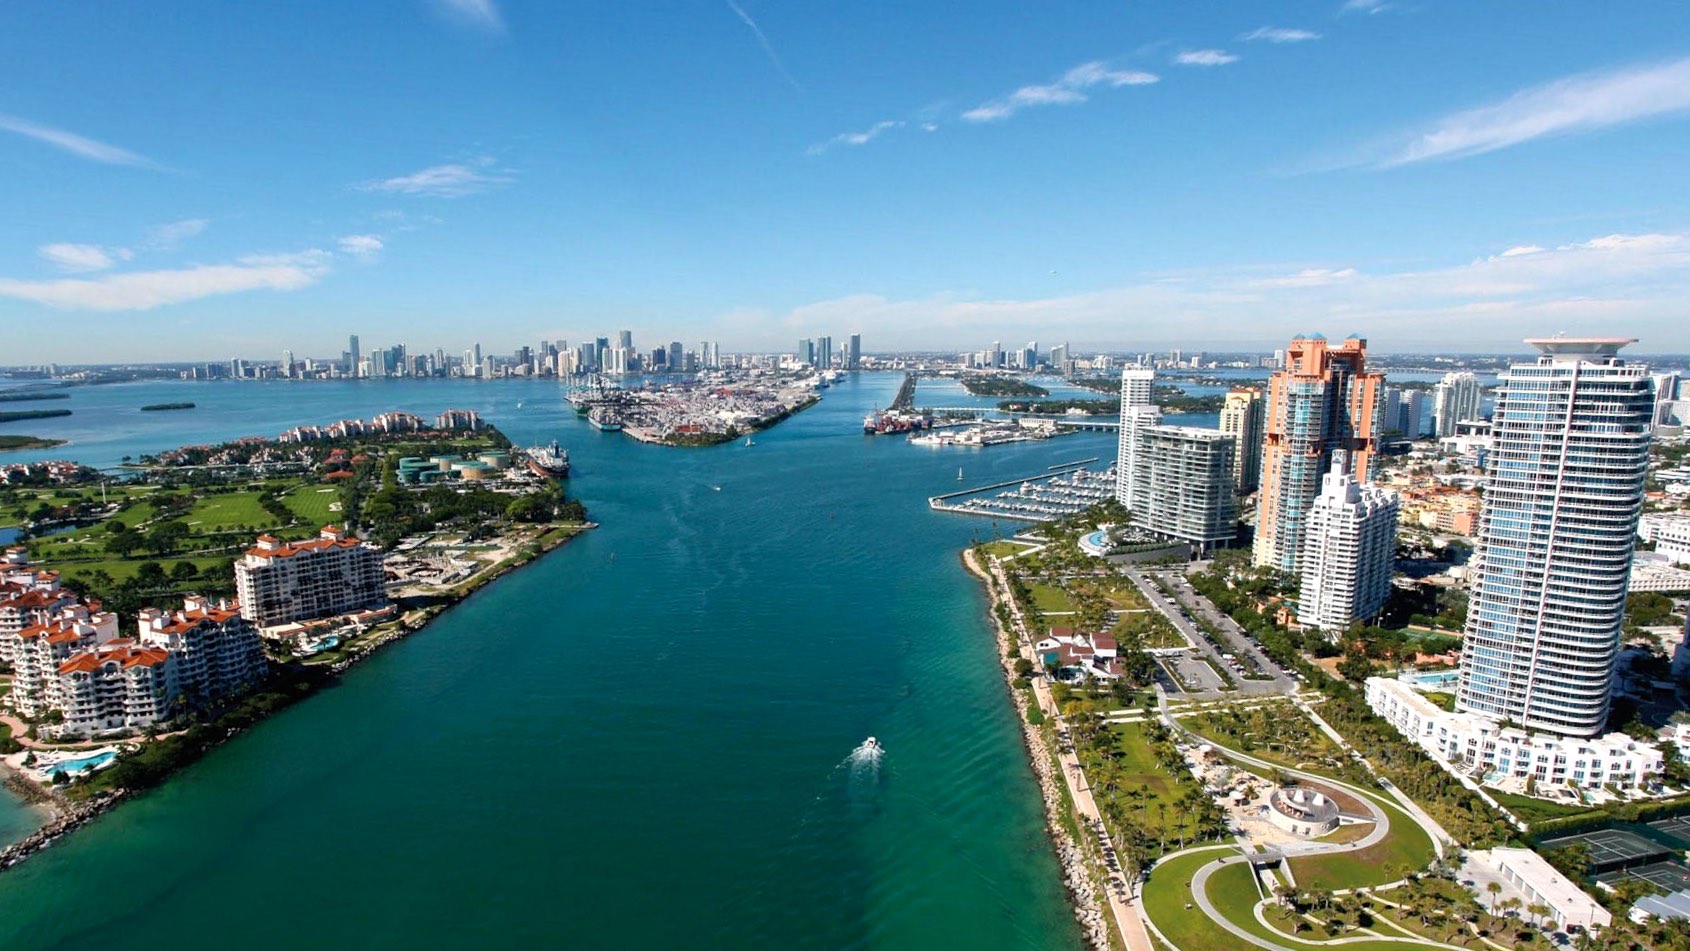
Averages say little about a particular house. What an insurer charges for a waterfront home in Miami Beach or Palm Beach depends on the building itself, and on paperwork that the seller may or may not have.
What to check before you sign
- Wind mitigation inspection. It records roof shape, roof-to-wall connections, and window and door protection. Credits for these features can change a premium substantially.
- Roof age and permits. Many carriers restrict cover for older roofs. The permit history matters as much as the roof's appearance.
- Four-point inspection of roof, electrical, plumbing and heating and cooling, usually required for older homes.
- Flood cover is separate. Standard homeowners policies exclude flood. Ask for the elevation certificate and the flood zone, and price flood insurance before you commit.
- The hurricane deductible is usually a percentage of the insured value, not a fixed sum. On a high-value home, the difference between two policies can be very large.
- For an apartment, read the association's master policy alongside your own unit policy. New lender rules now limit the deductible that can fall on each unit.
The order of operations
We ask a licensed insurance agent for an indicative quote before the inspection period ends, not after closing. If a house cannot be insured on reasonable terms, the family should know while it can still walk away.
Sources
- Florida Office of Insurance Regulation, January 13, 2026
- Citizens Property Insurance, 2026 rates, March 4, 2026
- Citizens Property Insurance, 2026 hurricane season coverage, June 23, 2026
- Spectrum News 13, July 30, 2026
This note is general information, not legal, tax, insurance or investment advice. Figures are as reported by the sources listed, on the dates shown.